Ask and ye shall receive:
Federal Reserve Bank lowers interest rate by half a percentage point.
Tuesday, September 18, 2007


SELLERS - IT'S NOT GETTING ANY BETTER!
http://www.msnbc.msn.com/id/20829849/
Updated: 1 hour, 30 minutes ago
LOS ANGELES - The number of foreclosure filings reported in the U.S. last month more than doubled versus August 2006 and jumped 36 percent from July, a trend that signals many homeowners are increasingly unable to make timely payments on their mortgages or sell their homes amid a national housing slump.
A total of 243,947 foreclosure filings were reported in August, up 115 percent from 113,300 in the same month a year ago, Irvine, Calif.-based RealtyTrac Inc. said Tuesday.
It may open the door for the Fed to be proactive and lower the FEDERAL FUNDS RATE a 1/4 or 1/2 point - that has not been done in 4 years! Will it help the average homeowner in the throes of foreclosure? Probably not. It will merely serve to increase demand for money, which will trickle down to somewhat lower interest rates.
The IRS is now getting involved...they have started a new section for homeowners losing their homes through foreclosure:
http://www.irs.gov/newsroom/article/0,,id=174022,00.html
Sellers, it's not pretty out there - you ARE COMPETING with thousands of other sellers, relocation companies, bank-owned properties, pre-foreclosures, and in-foreclosure properties. Make no mistake - values will continue to decline for the forseeable future as this "mess" continues to unfold.
If you think you are immune, think again. Some economists and real estate professionals are saying we have only seen the beginning on of the foreclosure fallout - the "tsunami" has yet to hit!
Best of luck to all...
http://www.msnbc.msn.com/id/20829849/
Updated: 1 hour, 30 minutes ago
LOS ANGELES - The number of foreclosure filings reported in the U.S. last month more than doubled versus August 2006 and jumped 36 percent from July, a trend that signals many homeowners are increasingly unable to make timely payments on their mortgages or sell their homes amid a national housing slump.
A total of 243,947 foreclosure filings were reported in August, up 115 percent from 113,300 in the same month a year ago, Irvine, Calif.-based RealtyTrac Inc. said Tuesday.
It may open the door for the Fed to be proactive and lower the FEDERAL FUNDS RATE a 1/4 or 1/2 point - that has not been done in 4 years! Will it help the average homeowner in the throes of foreclosure? Probably not. It will merely serve to increase demand for money, which will trickle down to somewhat lower interest rates.
The IRS is now getting involved...they have started a new section for homeowners losing their homes through foreclosure:
http://www.irs.gov/newsroom/article/0,,id=174022,00.html
Sellers, it's not pretty out there - you ARE COMPETING with thousands of other sellers, relocation companies, bank-owned properties, pre-foreclosures, and in-foreclosure properties. Make no mistake - values will continue to decline for the forseeable future as this "mess" continues to unfold.
If you think you are immune, think again. Some economists and real estate professionals are saying we have only seen the beginning on of the foreclosure fallout - the "tsunami" has yet to hit!
Best of luck to all...
Monday, September 03, 2007
JUST LISTED - 19 acre Horse Ranch in beautiful Odessa!


For more information, please email me for our full color, 11 page brochure detailing the amenities this rare property offers horse lovers.
To see the property, visit www.NorthCornerRanch.com

Asking $1.999M
This rare equine oasis is TURN-KEY, offering 22 stalls, a large 4/3 Ranch home, additional 3/3 apartment, and MUCH MORE!
Currently FULLY BOARDED, this property generates appr. $10,000 PER MONTH is boarding income.
For more information, please email me for our full color, 11 page brochure detailing the amenities this rare property offers horse lovers.
To see the property, visit www.NorthCornerRanch.com
Monday, August 27, 2007
Just when I thought I had seen it all...

With the advent of the Internet, marketing a home for sale has, to some, become a no-brainer. A flowery description, pictures, and a pri ce are all you need, right? Wrong.
A little while ago, I stopped calling myself a Sale Associate and started using the title "Real Estate Marketing Consultant". You might say "Oh, everyone want a title" but when you look at the actual meaning, the product I provide will make the difference between a home sale and a stale listing, a strong offer or a lowball. I earn my money not only by shuffling paperwork, but by how I market your home, where I market your home, and who sees your home. Simply put, I'm your PUBLICIST!#:
What makes my marketing so different from the 8600 other realtors in my county? I look at your home from the same context a buyer would - is it pretty? Is it clean? Do the pictures tell the story? Heck, does the main picture cause me to click to see more shots of the home
Here's a great example of a contrasting Main Home photos:

I was called to a listing appointment for a home that had been on the market for the course of 2 years...this was the picture of the home on the MLS before I took the listing...
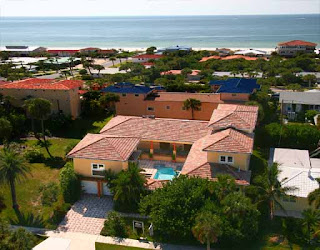
Here's the picture AFTER I took the listing:

I employed an aerial photgrapher because I could not capture the unique design on the home from the ground. i also wanted to illustrate just how close to the water this home really is - and I did it without words...
It's equally as important to know WHERE your home is being marketed. I like to target market. Let's take my $3M Beach home on the Gulf of mexico in Clearwater Beach. The MLS is great, but maybe this property needs to be market INTERNATONALLY. I know how to do it, what it costs, and have access to international advertising that the average homeowner doesn't. Sorry, it's a trade secret until you list with me!
Who sees your home is very important as well. I'm not going to market my new 19 acre Horse Farm listing to beach buyers. I am going to hit websites and publications catering to horse lovers, LLAMA LOVERS (because they need farms, too) and other equine-oriented venues.
In this market environment, you need a Real Estate Marketing Consultant who will show your property in the VERY BEST LIGHT...period
Monday, August 20, 2007
So what's this "Mortgage Mess" all about?
Simply put, the lax underwriting, increasing foreclosures, and fraudulent lending practices have made mortgage INVESTORS leary of buying blocks of mortgages. Without that influx of pure cash, the lenders cannot continue to lend - hence Countrywide's recent access of it's 11.5 BILLION line of credit.
Hard hit are "Jumbo" mortgage rates - any mortgage over $417,000, due to the uncertainty of investors with regard to the secondary market.
SELLERS TAKE NOTE: If you have the resources available and are in a good financial position, consider offering qualified buyers a PMM, or Purchase Money Mortgage. With rates from 6% - 9+%, offering a 1, 2, or 3 year balloon mortgage at 5.87% would be a dream for any buyer currently in the market and looking to pull the trigger on a higher dollar property.
Obviously, it's a little more complicated than that - a seller should only consider making the loan with a substantial down payment by the buyer - IMO, no less than 15%. Besides, the buyer's credit should be STELLAR with proof of employment and income verification.
What we have to do is take lemons and make lemonade - thinking outside the box is the American way!
Any questions, contact me...
Simply put, the lax underwriting, increasing foreclosures, and fraudulent lending practices have made mortgage INVESTORS leary of buying blocks of mortgages. Without that influx of pure cash, the lenders cannot continue to lend - hence Countrywide's recent access of it's 11.5 BILLION line of credit.
Hard hit are "Jumbo" mortgage rates - any mortgage over $417,000, due to the uncertainty of investors with regard to the secondary market.
SELLERS TAKE NOTE: If you have the resources available and are in a good financial position, consider offering qualified buyers a PMM, or Purchase Money Mortgage. With rates from 6% - 9+%, offering a 1, 2, or 3 year balloon mortgage at 5.87% would be a dream for any buyer currently in the market and looking to pull the trigger on a higher dollar property.
Obviously, it's a little more complicated than that - a seller should only consider making the loan with a substantial down payment by the buyer - IMO, no less than 15%. Besides, the buyer's credit should be STELLAR with proof of employment and income verification.
What we have to do is take lemons and make lemonade - thinking outside the box is the American way!
Any questions, contact me...
Wednesday, August 15, 2007
Florida’s housing market for 2Q 2007: Sales activity remains soft
Related story: NAR: Second-quarter homes prices improving but sales down in most states
ORLANDO, Fla. – Aug. 15, 2007 – In second quarter 2007, Florida's housing sector in many markets continued to report higher inventory levels of homes for sale, median prices edging down and sales activity reflecting a buyer’s market.
Statewide, sales of single-family existing homes totaled 37,709 during the three-month period, a decrease of 30 percent compared to 53,723 homes sold during the same time a year earlier, according to the Florida Association of Realtors® (FAR). The statewide existing-home median sales price was $239,200 in the second quarter; a year ago, it was $250,400 for a decrease of 4 percent. In 2002, the second-quarter statewide median sales price was $137,400, which reflects an increase of about 74.1 percent over the five-year period. The median is a typical market price where half the homes sold for more, half for less.
To gain insight into current trends in Florida’s real estate industry, the University of Florida’s Bergstrom Center for Real Estate Studies conducts a quarterly survey of industry executives, market research economists, real estate scholars and other experts. When assessing the state’s single-family markets, those polled in the second quarter 2007 survey viewed absorption activity as a sign the markets are continuing to move toward stability, said Dr. Wayne Archer, the center’s director. While acknowledging the potential impact of the subprime mortgage “meltdown” on Florida’s housing sector, along with the issues of property taxes and high insurance rates, Archer said, “Those of us who have watched markets for a long time realize the picture can change rather dramatically in a short period of time if something allows people to sell their house more quickly, such as a change in the property tax situation or a sudden improvement in the economy.”
Continuing low mortgage rates remain another positive influence on the housing market. According to Freddie Mac, the national commitment rate for a 30-year conventional fixed-rate mortgage averaged 6.37 percent in second quarter 2007; one year earlier, it averaged 6.60 percent.The latest industry outlook from the National Association of Realtors® (NAR) predicts that existing-home sales will continue to be stable over the next few months. Long-term fundamentals of the housing market remain favorable, said NAR Senior Economist Lawrence Yun, who expects a modest upturn for existing-home sales toward the end of the year.
“With the population growing, the demand for homes isn’t going away – it’s just being delayed,” Yun said. “More buyers, and cutbacks in new construction, will eventually draw down the inventory levels and support future price appreciation.”
Looking to Florida's existing condominium market, sales of existing condos also decreased during the quarter, with a total of 12,415 condos sold statewide compared to 16,566 in second quarter 2006 for a 25 percent decline, according to FAR. The statewide median sales price for condos remained relatively stable at $208,400 for the three-month period; a year ago, it was $211,200 for a 1 percent decline.Among the state’s larger markets, the Sarasota-Bradenton metropolitan statistical area (MSA) reported 2,365 existing homes sold for the quarter, a 4 percent increase compared to the 2,281 homes sold a year earlier. The market’s existing-home median sales price was $294,100; a year earlier, it was $318,500 for a decrease of 8 percent. A total of 948 existing condos sold in the market over the three-month period, up 2 percent from second quarter 2006, while the existing-condo median price decreased 9 percent to $246,900.
The Tallahassee MSA, one of the smaller markets in the state, reported that 1,178 homes changed hands in the second quarter, down 20 percent compared to 1,471 homes sold a year earlier. Over the same period, the market’s existing-home median home price rose 4 percent to $181,000; a year earlier, it was $174,800. A total of 102 existing condos sold in the Tallahassee area during the second quarter, a decrease of 30 percent from the previous year, while the existing-condo median price rose 4 percent to $153,600.
© 2007 FLORIDA ASSOCIATION OF REALTORS
Related story: NAR: Second-quarter homes prices improving but sales down in most states
ORLANDO, Fla. – Aug. 15, 2007 – In second quarter 2007, Florida's housing sector in many markets continued to report higher inventory levels of homes for sale, median prices edging down and sales activity reflecting a buyer’s market.
Statewide, sales of single-family existing homes totaled 37,709 during the three-month period, a decrease of 30 percent compared to 53,723 homes sold during the same time a year earlier, according to the Florida Association of Realtors® (FAR). The statewide existing-home median sales price was $239,200 in the second quarter; a year ago, it was $250,400 for a decrease of 4 percent. In 2002, the second-quarter statewide median sales price was $137,400, which reflects an increase of about 74.1 percent over the five-year period. The median is a typical market price where half the homes sold for more, half for less.
To gain insight into current trends in Florida’s real estate industry, the University of Florida’s Bergstrom Center for Real Estate Studies conducts a quarterly survey of industry executives, market research economists, real estate scholars and other experts. When assessing the state’s single-family markets, those polled in the second quarter 2007 survey viewed absorption activity as a sign the markets are continuing to move toward stability, said Dr. Wayne Archer, the center’s director. While acknowledging the potential impact of the subprime mortgage “meltdown” on Florida’s housing sector, along with the issues of property taxes and high insurance rates, Archer said, “Those of us who have watched markets for a long time realize the picture can change rather dramatically in a short period of time if something allows people to sell their house more quickly, such as a change in the property tax situation or a sudden improvement in the economy.”
Continuing low mortgage rates remain another positive influence on the housing market. According to Freddie Mac, the national commitment rate for a 30-year conventional fixed-rate mortgage averaged 6.37 percent in second quarter 2007; one year earlier, it averaged 6.60 percent.The latest industry outlook from the National Association of Realtors® (NAR) predicts that existing-home sales will continue to be stable over the next few months. Long-term fundamentals of the housing market remain favorable, said NAR Senior Economist Lawrence Yun, who expects a modest upturn for existing-home sales toward the end of the year.
“With the population growing, the demand for homes isn’t going away – it’s just being delayed,” Yun said. “More buyers, and cutbacks in new construction, will eventually draw down the inventory levels and support future price appreciation.”
Looking to Florida's existing condominium market, sales of existing condos also decreased during the quarter, with a total of 12,415 condos sold statewide compared to 16,566 in second quarter 2006 for a 25 percent decline, according to FAR. The statewide median sales price for condos remained relatively stable at $208,400 for the three-month period; a year ago, it was $211,200 for a 1 percent decline.Among the state’s larger markets, the Sarasota-Bradenton metropolitan statistical area (MSA) reported 2,365 existing homes sold for the quarter, a 4 percent increase compared to the 2,281 homes sold a year earlier. The market’s existing-home median sales price was $294,100; a year earlier, it was $318,500 for a decrease of 8 percent. A total of 948 existing condos sold in the market over the three-month period, up 2 percent from second quarter 2006, while the existing-condo median price decreased 9 percent to $246,900.
The Tallahassee MSA, one of the smaller markets in the state, reported that 1,178 homes changed hands in the second quarter, down 20 percent compared to 1,471 homes sold a year earlier. Over the same period, the market’s existing-home median home price rose 4 percent to $181,000; a year earlier, it was $174,800. A total of 102 existing condos sold in the Tallahassee area during the second quarter, a decrease of 30 percent from the previous year, while the existing-condo median price rose 4 percent to $153,600.
© 2007 FLORIDA ASSOCIATION OF REALTORS
DOUBLE CORNER LOT FOR SALE - NEW LISTING IN ST. PETERSBURG
1501 41st Ave N


1501 41st Ave N

DOUBLE CORNER LOT! DOUBLE CORNER LOT! 2 BR, 1 BA home on a double corner lot! Newly refinished - hardwood floors in both BRs, neutral paint and tile floors throughout. Sunroom off of the kitchen can be used as 3rd BR with French doors. 1 Car garage, NEW roof in 2002, newer rebuilt air handler/compressor. Adorable bungalow style with curved archways. Super-clean house in terrific St. Pete neighborhood! One street away from Historic Allendale Terrace. Close to highway (I-275), many schools and downtown St. Petersburg.
$169,900 - call for more info, details, and pics

Monday, August 06, 2007
So, what kind of market are we in?
No matter what the papers say, no matter what Realtors, say, no matter what your uncle's brother's cousin (twice-removed) says...we are still in a DEPRECIATING MARKET.
How can I say that you ask...let's look at the raw numbers from Pinellas County Homes & Condos from May '06 - June '07:

The easiest characteristic of a DECLINING VALUE MARKET is the inventory vs. absorption (solds). Notice the steadily increasing inventory of properties for sale - then contrast it tour the declining (or flatlining) number of SOLD properties.
So what IS happening to prices? Good question - let's take a look:

Haven't you heard prices are falling? Apparently not, looking at this cumulative graph over the past year. Look at the red line for 04/06 - Average price of $272,000. Go to the far right and look at 06/07 - $272,000. Hmmm...that tells me that prices are holding SOMEWHAT STEADY if you take a macro viewpoint. Someneighborhoods have seen 20% - 30% decreases.
Notice the declining GREEN line...those are asking prices. They have steadily fallen as Sellers realize they are competing against each other for the savvy buyers. Average ASKING prices have fallen appr. 18% in Pinellas County - NOTE I said ASKING PRICES, not necessarily sales prices.
So what's going to happen - honestly, that's anyone's guess. However, if you look at the numbers of For Sales, Pendings, and Solds (Graph #1) over the last 3-5 months, you will notice they do not change much month over month - that indicates stabilization in our market place.
Buyers, it's probably about hit bottom - maybe another 5%, which you can easily capture with good negotiating. Sellers, if you get an offer 5%-7% b elow your already "low" asking price, don't be insulted - it's simply the market.
Good luck!
Monday, July 30, 2007
ATTENTION SELLERS:
http://www.floridarealtors.org/NewsAndEvents/n2-073007.cfm
Study: Foreclosures impact entire neighborhoodsMIAMI
– July 30, 2007 –
Mounting mortgage defaults across South Florida threaten to hurt more than just those homeowners who lose their properties to lenders.
Experts say foreclosures could drag down already sluggish housing prices throughout entire neighborhoods.
“Homeowners that are being foreclosed upon aren’t spending their Saturday afternoons mowing the yard,” said Greg McBride, a senior financial analyst at Bankrate.com in North Palm Beach. “So those people who are cutting the grass, trimming the shrubs and fixing the gutters will suffer.”
In the Tree Tops development in Wellington, where residents tend to their lots with care, one property near the entrance is in foreclosure and has been on the market for months. The vacant house has a rickety wooden fence, missing roof tiles and, until recently, a front yard full of weeds. A buyer just walked away from a $190,000 contract on the home, located about three miles west of the Mall at Wellington Green where comparable homes go for as much has $240,000.
As a result, neighbors trying to sell their wood-frame homes built in the early 1980s could have a hard time getting their asking prices, said Deanne Lee, 43, a real estate agent who lives one street from the house in foreclosure.
“It’s a scary thought,” Lee said. “I see this as just the beginning.”
In a national study published last year, two housing analysts found that for every foreclosure within one-eighth of a mile of a single-family home, property values decline by about 1 percent, and even more in dense developments. The study by Geoff Smith and Dan Immergluck is thought to be the only comprehensive look at the effect of foreclosures on property values, and is based on depressed values in Chicago in 1997 and 1998. Based on their study, the value of a typical Palm Beach County home near one property in foreclosure could drop at least $3,779. The county’s median-priced existing home in June was $377,900, according to the Florida Association of Realtors.
“One foreclosure may have a modest effect on nearby property values, but with four or five foreclosures, you’ll see a significant effect,” said Smith, director of the Woodstock Institute, a nonprofit housing group in Chicago. “You see neighborhoods start to decline.”
Smith recommends that neighbors of foreclosed homes postpone selling their own properties until the housing market improves. “But people often times don’t have that option,” he said.The numbers of homeowners defaulting on their mortgages and facing foreclosure are rising steadily across South Florida this year, according to Realestat.com, a Plantation-based company that compiles local housing statistics.
Analysts mostly blame the trouble on unconventional home loans made to risky borrowers hoping to get into houses and condominiums that shot up in value during the housing boom from 2000 to 2005.
Perfect foreclosure storm
The umber of Palm Beach County homeowners behind on their mortgage payments topped 1,000 in June, almost a fourfold increase from 259 a year ago. Actual foreclosures were flat last month. The worst is yet to come, however. Experts say foreclosure filings and late-payment notices from lenders are expected to peak this fall, leaving lenders with a glut of properties to sell by next summer.In Floral Park, a middle-class development of 40-year-old homes in suburban Lake Worth, a foreclosed house went on the market down the street from Joe Rodriguez. It sold recently for just more than $263,000.
As a result, Rodriguez is worried that he could have a hard time getting his $369,900 asking price, even though his four-bedroom corner property is bigger and includes a pool table as an incentive.
“It’s a bad sign,” Rodriguez said of foreclosures. “If the banks turn around and sell them for less, sure, it’s going to hurt [other sellers nearby.]”
Homeowners with late house payments usually are at least three months behind and have been notified that their lenders intend to foreclose. In many cases, people who secured adjustable-rate loans found they couldn’t afford the monthly payments once interest rates rose.During the housing frenzy, some of those people avoided foreclosure simply by selling the homes or refinancing. But that wasn’t as easy to do when the market slumped last year. With fewer buyers and thousands of properties for sale, cash-strapped homeowners can’t count on fast deals to bail them out of trouble.
What’s more, refinancing isn’t as easy now because home values are flat or dropping and lenders are tightening credit standards as borrowers default on home loans.Neighborhoods that stand to get hurt the most from the foreclosure crunch are newer ones with a large number of sales made near the peak of the housing boom in 2005, said Alan Hunter, a senior market analyst with Metrostudy, a West Palm Beach consulting firm.
Because lenders don’t want to be in the real estate business, they’ll likely sell those properties quickly and at a loss that will reduce home values.
“They’ll be bought by investors who will try to rent them out at a profit,” Hunter said.It’s becoming more difficult to determine whether price declines are the result of nearby foreclosures or the general decline in the housing market, real estate agents say. Regardless, the downward pressure on prices actually will be good in the long run for overpriced markets, including South Florida, said Mark Vitner, senior economist for Wachovia Securities.“It’s going to help speed up the adjustment process,” Vitner said. “More homes will get into the hands of more willing sellers – the banks or whomever. It’s a necessary thing.”
But that’s not what sellers want to hear. Re/Max agent Mark Plaxen is marketing a two-bedroom townhouse off Village Boulevard in West Palm Beach. Four months ago, the seller was asking $199,000 but has since reduced the price five times. This month it was listed at $174,900.
Plaxen just found out about another listing in the same development: a townhouse in foreclosure.“I’ll probably have to call up my seller and say, ‘It’s time to lower the price again.’”
Copyright © 2007 South Florida Sun-Sentinel, Paul Owers. Distributed by McClatchy-Tribune Information Services.
http://www.floridarealtors.org/NewsAndEvents/n2-073007.cfm
Study: Foreclosures impact entire neighborhoodsMIAMI
– July 30, 2007 –
Mounting mortgage defaults across South Florida threaten to hurt more than just those homeowners who lose their properties to lenders.
Experts say foreclosures could drag down already sluggish housing prices throughout entire neighborhoods.
“Homeowners that are being foreclosed upon aren’t spending their Saturday afternoons mowing the yard,” said Greg McBride, a senior financial analyst at Bankrate.com in North Palm Beach. “So those people who are cutting the grass, trimming the shrubs and fixing the gutters will suffer.”
In the Tree Tops development in Wellington, where residents tend to their lots with care, one property near the entrance is in foreclosure and has been on the market for months. The vacant house has a rickety wooden fence, missing roof tiles and, until recently, a front yard full of weeds. A buyer just walked away from a $190,000 contract on the home, located about three miles west of the Mall at Wellington Green where comparable homes go for as much has $240,000.
As a result, neighbors trying to sell their wood-frame homes built in the early 1980s could have a hard time getting their asking prices, said Deanne Lee, 43, a real estate agent who lives one street from the house in foreclosure.
“It’s a scary thought,” Lee said. “I see this as just the beginning.”
In a national study published last year, two housing analysts found that for every foreclosure within one-eighth of a mile of a single-family home, property values decline by about 1 percent, and even more in dense developments. The study by Geoff Smith and Dan Immergluck is thought to be the only comprehensive look at the effect of foreclosures on property values, and is based on depressed values in Chicago in 1997 and 1998. Based on their study, the value of a typical Palm Beach County home near one property in foreclosure could drop at least $3,779. The county’s median-priced existing home in June was $377,900, according to the Florida Association of Realtors.
“One foreclosure may have a modest effect on nearby property values, but with four or five foreclosures, you’ll see a significant effect,” said Smith, director of the Woodstock Institute, a nonprofit housing group in Chicago. “You see neighborhoods start to decline.”
Smith recommends that neighbors of foreclosed homes postpone selling their own properties until the housing market improves. “But people often times don’t have that option,” he said.The numbers of homeowners defaulting on their mortgages and facing foreclosure are rising steadily across South Florida this year, according to Realestat.com, a Plantation-based company that compiles local housing statistics.
Analysts mostly blame the trouble on unconventional home loans made to risky borrowers hoping to get into houses and condominiums that shot up in value during the housing boom from 2000 to 2005.
Perfect foreclosure storm
The umber of Palm Beach County homeowners behind on their mortgage payments topped 1,000 in June, almost a fourfold increase from 259 a year ago. Actual foreclosures were flat last month. The worst is yet to come, however. Experts say foreclosure filings and late-payment notices from lenders are expected to peak this fall, leaving lenders with a glut of properties to sell by next summer.In Floral Park, a middle-class development of 40-year-old homes in suburban Lake Worth, a foreclosed house went on the market down the street from Joe Rodriguez. It sold recently for just more than $263,000.
As a result, Rodriguez is worried that he could have a hard time getting his $369,900 asking price, even though his four-bedroom corner property is bigger and includes a pool table as an incentive.
“It’s a bad sign,” Rodriguez said of foreclosures. “If the banks turn around and sell them for less, sure, it’s going to hurt [other sellers nearby.]”
Homeowners with late house payments usually are at least three months behind and have been notified that their lenders intend to foreclose. In many cases, people who secured adjustable-rate loans found they couldn’t afford the monthly payments once interest rates rose.During the housing frenzy, some of those people avoided foreclosure simply by selling the homes or refinancing. But that wasn’t as easy to do when the market slumped last year. With fewer buyers and thousands of properties for sale, cash-strapped homeowners can’t count on fast deals to bail them out of trouble.
What’s more, refinancing isn’t as easy now because home values are flat or dropping and lenders are tightening credit standards as borrowers default on home loans.Neighborhoods that stand to get hurt the most from the foreclosure crunch are newer ones with a large number of sales made near the peak of the housing boom in 2005, said Alan Hunter, a senior market analyst with Metrostudy, a West Palm Beach consulting firm.
Because lenders don’t want to be in the real estate business, they’ll likely sell those properties quickly and at a loss that will reduce home values.
“They’ll be bought by investors who will try to rent them out at a profit,” Hunter said.It’s becoming more difficult to determine whether price declines are the result of nearby foreclosures or the general decline in the housing market, real estate agents say. Regardless, the downward pressure on prices actually will be good in the long run for overpriced markets, including South Florida, said Mark Vitner, senior economist for Wachovia Securities.“It’s going to help speed up the adjustment process,” Vitner said. “More homes will get into the hands of more willing sellers – the banks or whomever. It’s a necessary thing.”
But that’s not what sellers want to hear. Re/Max agent Mark Plaxen is marketing a two-bedroom townhouse off Village Boulevard in West Palm Beach. Four months ago, the seller was asking $199,000 but has since reduced the price five times. This month it was listed at $174,900.
Plaxen just found out about another listing in the same development: a townhouse in foreclosure.“I’ll probably have to call up my seller and say, ‘It’s time to lower the price again.’”
Copyright © 2007 South Florida Sun-Sentinel, Paul Owers. Distributed by McClatchy-Tribune Information Services.
Thursday, July 05, 2007
http://realestate.msn.com/Buying/Article_Forbes.aspx?cp-documentid=5008065>1=10130
Where will real estate bounce back fastest?
Prices have hit bottom in some cities and are heading back up, but recovery rates vary. Here are the places with the best prospects.
By Matt Woolsey, Forbes.com
When it comes to real estate, the questions on everyone's lips are: How low is low, and when's the perfect time to buy back in?
That moment has passed in Seattle and in Charlotte, N.C. Both metro areas hit bottom in the first quarter of 2006 and have since posted price gains of 12.3% and 6.3%, respectively, according to National Association of Realtors (NAR) data.
Ripe for investment? Philadelphia and New Orleans. Based on housing inventory and local economic conditions, both should hit price troughs by year's end and bounce back with moderate gains of around 4% in 2008.
In markets expected to recover more slowly, such as Boston and Denver, low buyer confidence coupled with a surplus of housing stock has lengthened the slump. NAR chief economist Lawrence Yun points out that buyers are looking for clear signs of a market bottom and are content to wait on the sidelines until then.
It's easy to see why. Most of the country's real-estate markets are feeling the effects of overproduction. A strong market hovers near a 1.5% vacancy rate, but the national average currently stands at 2.8%, and in cities such as Miami, Atlanta and Denver, figures hang around 3.5%. In addition, every nugget of good news (like the May Commerce Department report that said new-home sales are at a 14-year high) comes with bad news (median price growth is at a 10-year low).
So which other metro area markets stand the best chance of recovery, and when will that upturn occur?
Behind the numbers
Market corrections follow three basic recovery patterns: a V-shaped recovery where a market experiences a sharp, fast decline but comes out strong once it hits bottom; a U-shaped recovery, where prices decline gradually and recover slowly; and an L-shaped pattern, a hard, fast fall with a paltry price bounce-back after the market trough.
The differences between a V-shaped market and a U-shaped one have to do with barriers to growth. High vacancy rates and high investor share can hurt a market, but if the local economy remains strong and housing stock affordable, it's only a matter of how long it takes to absorb the excess inventory.
Tampa, Fla., is a perfect candidate for a V-shaped recovery, according to research from Moody's Economy.com, an economic analysis, forecasting and credit risk firm in West Chester, Pa. The local economy remains strong, and subprime lending is relatively low. Tampa's problem? A high investor share that led to high vacancy rates. When the market turned sour in 2005, more than 25% of Tampa homes were owned as investment properties. Investors are quicker to flee during a downturn, thus creating a glut of available housing stock. In Tampa's case, vacancy rates now stand at 3.5%.
"As investors exit, the market revives," says Mark Zandi, chief economist at Moody's Economy.com, as fewer speculative buyers result in a more stable market. "Tampa's a pretty affordable market, and first-time buyers can come in once prices fall."
Based on Moody's Economy projections, Tampa should burn off its excess inventory and hit a price trough in the first quarter of 2008, at which point prices are expected to increase by 10.6% the following year.
These projections take into account housing affordability, vacancy rates, the strength of the local economy and job market, investor share in 2005 and the share of subprime mortgages. Data are from Moody's, the Bureau of Labor Statistics and the Federal Reserve.
Predicting the bottom of any asset market, especially real estate, is a difficult thing. While these projections are based on sound data and advanced modeling by Moody's, no one can predict futures markets with absolute certainty.
Other bounces
Like Tampa, Phoenix is afflicted by high investor share (26.1%), and it has a vacancy rate of more than 3%. Good affordability rates and a surging job market suggest that once Phoenix bottoms out, price growth will be strong. Moody's projection model has Phoenix reaching its price trough in the fourth quarter of 2008 and then growing by 7.7% the following year.
Slower recovery rates are expected in markets such as Minneapolis and Boston, where a slumping local economy, slow job growth and negative migration numbers hamper long-term prospects. Along with other U-shaped markets, like Sacramento, that have double-digit subprime lending share, Zandi says it's going to be harder for these markets to get going again.
That doesn't necessarily mean V-shaped markets are in the clear. The labor markets in cities such as Las Vegas, Phoenix and San Diego, whose future economic success will be critical to recovery, are heavily in housing-related industries, according to Moody's. So long as those economies can weather their respective corrections, they should be all right.
"These markets are going to experience more substantial declines in the coming year," says Zandi. "Gauging the bottom is a very intrepid affair, and the job market is very important to recovery."
Real-estate markets with the best prospects for recovery
Rank
Market
Expected market bottom
Est. price appreciation after bottom
1
Tampa, Fla.
Q1 2008
10.60%
2
Phoenix
Q4 2008
7.70%
3
Las Vegas
Q2 2009
7.20%
4
San Diego
Q2 2008
5.30%
5
New Orleans
Q3 2007
4.30%
Monday, July 02, 2007
Ever wanted to compare HOME INSURANCE rates, just like certain car insurance companies??? Well, now YOU can...
http://www.shopandcomparerates.com/HOCompareRates.htm
Sponsored by the State of Florida, this interactive website will give you a list of top insurance providers in each county.
Call and shop around for a policy that saves you $$$...enjoy!
FYI: prices for most properties have decreased to 2005 or 2004 levels - now is a terrific time to buy and lock in savings. If you are looking for something specific, please call or email me to get started - it's so easy and you can thank me later!
http://www.shopandcomparerates.com/HOCompareRates.htm
Sponsored by the State of Florida, this interactive website will give you a list of top insurance providers in each county.
Call and shop around for a policy that saves you $$$...enjoy!
FYI: prices for most properties have decreased to 2005 or 2004 levels - now is a terrific time to buy and lock in savings. If you are looking for something specific, please call or email me to get started - it's so easy and you can thank me later!
SELLERS:
With interest rates at a 10-month high, consider offering buyers an incentive - buy down their mortgage rate and they'll be happy as a clam! If you're using a realtor, ask them for to contact a trusted mortgage lender and get a quote for several different buydown options. If your braving this depreciatin market alone, then contact a trusted mortgage lender (if you have one) and ask for buydown quotes. Remember, realtors have tried-and-true referral lists for just these types of things...
It's a terrific way to get an edge in a market saturated with competition. However, it will not substitute for ENERGY-PRICING, i.e. pricing your home to sell and not just being an "MLS super-star".
best of luck...Rich C
With interest rates at a 10-month high, consider offering buyers an incentive - buy down their mortgage rate and they'll be happy as a clam! If you're using a realtor, ask them for to contact a trusted mortgage lender and get a quote for several different buydown options. If your braving this depreciatin market alone, then contact a trusted mortgage lender (if you have one) and ask for buydown quotes. Remember, realtors have tried-and-true referral lists for just these types of things...
It's a terrific way to get an edge in a market saturated with competition. However, it will not substitute for ENERGY-PRICING, i.e. pricing your home to sell and not just being an "MLS super-star".
best of luck...Rich C
Oh wow, things have been cooking in my neck of the woods. I mentioned in my last post that I have just joined Coldwell Banker Residential RE in Clearwater. My client response has been overwhelmingly positive and encouraging. So much so that every one of my sellers have decided to allow Coldwell Banker to continue marketing their homes.
At the risk of sounding like a Coldwell Banker "mark", they do have so much to offer that the learning curve is DAUNTING - but I've jumped right in and I'm having a blast.
Here's what's new:
NEW LISTINGS NEW LISTINGS NEW LISTINGS


At the risk of sounding like a Coldwell Banker "mark", they do have so much to offer that the learning curve is DAUNTING - but I've jumped right in and I'm having a blast.
Here's what's new:
NEW LISTINGS NEW LISTINGS NEW LISTINGS


820 Eldorado Avenue on Clearwater's MOST FAMOUS BEACH...Gulf-front 4/3, 3190 sf, multiple underbuilding parking. Phenomenally re-designed: Italian Cucini kitchen, Spa-like Master Bath, rebuilt Gulf-front lanai...so much more! $2,999,000...the LOWEST price per sf on the Gulf in Clw Beach


7430 Sunshine Skyway Lane S #902 at the Southern tip of St. Petersburg...TOP FLOOR 2/2, 1100 sf, dramatic water views...wow ....$289,000
Prices are dropping and Buyers abound (really) - BUT they are savvy and will NOT pay more than a home is worth - in fact, buyers are making under-value offers in hopes of not losing value once they move in. In our previously appreciating market, even if a home were priced too high, eventually the price point would rise high enough to meet that home's asking price - the exact opposite is now occurring. The price point continues to erode, yet many seller's pries are still above the market level. In this instance, the gap continually widens every day the market continues its descent to normal valuations.
What does this mean for you??? Sellers, get your stuff together and get those prices DOWN.
Unless you want to hold onto the property for an untold number of years to come, minimize those losses and price the property competitively - in many cases, that means being THE LEAST EXPENSIVE home on the block.
It's called "ENERGY-PRICING" and it creates a perceived sense of value for buyers...
Happy hunting!
Rich
Prices are dropping and Buyers abound (really) - BUT they are savvy and will NOT pay more than a home is worth - in fact, buyers are making under-value offers in hopes of not losing value once they move in. In our previously appreciating market, even if a home were priced too high, eventually the price point would rise high enough to meet that home's asking price - the exact opposite is now occurring. The price point continues to erode, yet many seller's pries are still above the market level. In this instance, the gap continually widens every day the market continues its descent to normal valuations.
What does this mean for you??? Sellers, get your stuff together and get those prices DOWN.
Unless you want to hold onto the property for an untold number of years to come, minimize those losses and price the property competitively - in many cases, that means being THE LEAST EXPENSIVE home on the block.
It's called "ENERGY-PRICING" and it creates a perceived sense of value for buyers...
Happy hunting!
Rich
Tuesday, June 19, 2007
Leaving a brokerage in favor of another is like leaving your parents home when your 18...you know your ready to leave, you realize there is so much more out there for you, but the trepidation of leaving the "comfort level" of the brokerage is nerve-wracking and downright scary!
So now, as I prepare to leave the nest, I would like to inform my valuable clients, friends, and family that I have proudly joined the Coldwell Banker Residential Real Estate family! Aside from my brokerage affiliation, none of my personal contact info will change - my email, cell phone, website, logo, and vendor affiliations will stay the same. I will have a new office phone and fax number.
Here's what will change:
Here's a few questions you may have:
Will Rich Cornelius be able to serve his clientele as well as before?
Will Rich Cornelius be able to offer his Sellers more advertising visibility for their homes?
Will Rich Cornelius be able to offer enhanced services to his Buyers?
The answer to the above questions is a resounding "YES" - my hope is that all of my clients make the transition with me so they can personally experience the difference.
If you have any questions, please call 727.417.8814 or email me at your convenience...
So now, as I prepare to leave the nest, I would like to inform my valuable clients, friends, and family that I have proudly joined the Coldwell Banker Residential Real Estate family! Aside from my brokerage affiliation, none of my personal contact info will change - my email, cell phone, website, logo, and vendor affiliations will stay the same. I will have a new office phone and fax number.
Here's what will change:
- I will be able to offer my sellers increased Internet visibility exclusively provided to CB agents such as ColdwellBanker.com, FloridaMoves.com, and EVEN http://www.nytimes.com/.
- Showings will be scheduled by the Coldwell Banker call center vs. a message on my cell phone (I sometimes miss calls while with clients or on lengthy appointments).
- I will be offered cutting-edge Continuing Education classes to harness the latest technology in buying and selling real estate.
- Color advertising on the FRONT PAGE OF THE ST. PETERSBURG TIME REAL ESTATE SECTION - only available through Coldwell Banker.
- Access to innovative, proprietary software called TrendGraphix, which instantly illustrates various real estate trends at the click of the mouse.
Here's a few questions you may have:
Will Rich Cornelius be able to serve his clientele as well as before?
Will Rich Cornelius be able to offer his Sellers more advertising visibility for their homes?
Will Rich Cornelius be able to offer enhanced services to his Buyers?
The answer to the above questions is a resounding "YES" - my hope is that all of my clients make the transition with me so they can personally experience the difference.
If you have any questions, please call 727.417.8814 or email me at your convenience...
Friday, June 15, 2007
This is a special blog post......
The Florida Legislature announced yesterday they have voted on and passed comprehensive tax relief for Florida homeowners. Some decry it a not enough while others say the cuts go to far...only the future can tell. As a recently new homeowner myself, I will see my property tax bill decrease substantially - from $5100 to $2200. If you have the Save Our Homes cap and have a tax bill LOWER than what the new legislation amount would be, you CAN KEEP YOUR ORIGINAL TAX AMOUNT. Should you decide, for whatever reason, to switch to the new "Super-exemption", you can - but you cannot go back to Save Our Homes.
Here's an exercpt from the St. Pete Times http://www.sptimes.com/2007/06/15/State/QA__Lower_bill_won_t_.shtml:
When will I see lower taxes?
In November, the tax bill you get will be an average of about 7 percent lower than it was last year. This is the result of the rollback plan and tax cap that was approved by lawmakers Thursday. It requires local governments to reduce their tax collections.
I thought the plan was in trouble. What happened?
The rollback plan never was in trouble, but the proposal to create a new "superhomestead" exemption to replace Save Our Homes had drawn skepticism from some GOP senators. Very late Wednesday night, lawmakers agreed to one final change that provided the comfort the skeptics needed to support the new homestead plan, and they did.
That change will allow homeowners to decide between keeping the existing Save Our Homes tax cap, which favors longtime owners, and the new superhomestead, which would offer the best tax breaks for relative newcomers.
So, is it all done?
Not exactly. The rollback needs only the signature of Gov. Charlie Crist, who will likely sign it soon, but the homestead exemption change must be approved by Florida voters. It will appear on the ballot Jan. 29, the day Florida holds its presidential primary.
However, since it's an amendment to the state Constitution, the new homestead plan will have to win a 60 percent majority, which is a very high threshold. Not many constitutional amendments have been that popular.
So, how would the superhomestead exemption work?
Under the proposal, 75 percent of the first $200, 000 in home value would be exempt from taxation. Then another 15 percent of the next $300, 000 in home value would be tax exempt. A minimum exemption of $50, 000 would be guaranteed for homes worth less than $200, 000, and a maximum exemption of $195, 000 would guaranteed for homes worth more than $500, 000.
When will I get to decide between keeping Save Our Homes and taking the new superhomestead?
Not until after the Jan. 29 election. If voters approve the new superhomestead, then homeowners will have a decision to make.
How will that process work?
The details are still to be ironed out, but here's what we know: The Save Our Homes exemption will remain on your house until you decide to switch. If you want to have the superhomestead applied to your house, you will have to contact county officials, probably your tax collector, and let them know. But, once you've switched to the new homestead, you won't be able to switch back.
How long would I be able to keep Save Our Homes?
For as long as you live in your house. Once you move, you would lose your Save Our Homes exemption and you would be switched to the new superhomestead.
How will I decide between taking the new superexemption and sticking with Save Our Homes?
That's a tricky question. For most homeowners, the new exemption would lower your tax bill right away. But it is possible that Save Our Homes could be a better deal on your tax bill over the long term. Even though the new homestead exemption offers a steep cut in the taxable value on your home, that may not be as beneficial as having the Save Our Homes cap, especially in areas where property values are likely to keep rising.
When they talk about "rolling back" taxes for cities and counties, what exactly would get rolled back?
The "rollback" refers to the revenue that cities and counties collect from property taxes; it's not the entire budget. Local governments also raise money through such things as fees and franchise agreements with cable companies, which wouldn't be affected. Still, property taxes are an enormous part of a local government's revenue stream, and property taxes also fund an array of specialty taxing districts for such things as mosquito control and hospital service. All of those tax-raising groups would have to roll back their tax rates.
What about school districts?
School districts would be exempt from the rollback.
How much money would I get back under the rollback?There are tons of variables for individuals because each city and county has many different taxing districts with many different tax rates. But lawmakers have calculated a statewide average of $174 for homeowners. Commercial land owners would save $941.
Can my local government refuse to lower my tax bill and override these plans?
Yes, but it's difficult. Depending on the cuts they want to override, they will need anywhere between a simple majority to a unanimous vote. Also, if they want to raise your taxes, they would have to ask first by a public referendum.
Calculate you new taxes below:
http://www.sptimes.com/2007/webspecials07/graphics/taxbill-calc/
The Florida Legislature announced yesterday they have voted on and passed comprehensive tax relief for Florida homeowners. Some decry it a not enough while others say the cuts go to far...only the future can tell. As a recently new homeowner myself, I will see my property tax bill decrease substantially - from $5100 to $2200. If you have the Save Our Homes cap and have a tax bill LOWER than what the new legislation amount would be, you CAN KEEP YOUR ORIGINAL TAX AMOUNT. Should you decide, for whatever reason, to switch to the new "Super-exemption", you can - but you cannot go back to Save Our Homes.
Here's an exercpt from the St. Pete Times http://www.sptimes.com/2007/06/15/State/QA__Lower_bill_won_t_.shtml:
When will I see lower taxes?
In November, the tax bill you get will be an average of about 7 percent lower than it was last year. This is the result of the rollback plan and tax cap that was approved by lawmakers Thursday. It requires local governments to reduce their tax collections.
I thought the plan was in trouble. What happened?
The rollback plan never was in trouble, but the proposal to create a new "superhomestead" exemption to replace Save Our Homes had drawn skepticism from some GOP senators. Very late Wednesday night, lawmakers agreed to one final change that provided the comfort the skeptics needed to support the new homestead plan, and they did.
That change will allow homeowners to decide between keeping the existing Save Our Homes tax cap, which favors longtime owners, and the new superhomestead, which would offer the best tax breaks for relative newcomers.
So, is it all done?
Not exactly. The rollback needs only the signature of Gov. Charlie Crist, who will likely sign it soon, but the homestead exemption change must be approved by Florida voters. It will appear on the ballot Jan. 29, the day Florida holds its presidential primary.
However, since it's an amendment to the state Constitution, the new homestead plan will have to win a 60 percent majority, which is a very high threshold. Not many constitutional amendments have been that popular.
So, how would the superhomestead exemption work?
Under the proposal, 75 percent of the first $200, 000 in home value would be exempt from taxation. Then another 15 percent of the next $300, 000 in home value would be tax exempt. A minimum exemption of $50, 000 would be guaranteed for homes worth less than $200, 000, and a maximum exemption of $195, 000 would guaranteed for homes worth more than $500, 000.
When will I get to decide between keeping Save Our Homes and taking the new superhomestead?
Not until after the Jan. 29 election. If voters approve the new superhomestead, then homeowners will have a decision to make.
How will that process work?
The details are still to be ironed out, but here's what we know: The Save Our Homes exemption will remain on your house until you decide to switch. If you want to have the superhomestead applied to your house, you will have to contact county officials, probably your tax collector, and let them know. But, once you've switched to the new homestead, you won't be able to switch back.
How long would I be able to keep Save Our Homes?
For as long as you live in your house. Once you move, you would lose your Save Our Homes exemption and you would be switched to the new superhomestead.
How will I decide between taking the new superexemption and sticking with Save Our Homes?
That's a tricky question. For most homeowners, the new exemption would lower your tax bill right away. But it is possible that Save Our Homes could be a better deal on your tax bill over the long term. Even though the new homestead exemption offers a steep cut in the taxable value on your home, that may not be as beneficial as having the Save Our Homes cap, especially in areas where property values are likely to keep rising.
When they talk about "rolling back" taxes for cities and counties, what exactly would get rolled back?
The "rollback" refers to the revenue that cities and counties collect from property taxes; it's not the entire budget. Local governments also raise money through such things as fees and franchise agreements with cable companies, which wouldn't be affected. Still, property taxes are an enormous part of a local government's revenue stream, and property taxes also fund an array of specialty taxing districts for such things as mosquito control and hospital service. All of those tax-raising groups would have to roll back their tax rates.
What about school districts?
School districts would be exempt from the rollback.
How much money would I get back under the rollback?There are tons of variables for individuals because each city and county has many different taxing districts with many different tax rates. But lawmakers have calculated a statewide average of $174 for homeowners. Commercial land owners would save $941.
Can my local government refuse to lower my tax bill and override these plans?
Yes, but it's difficult. Depending on the cuts they want to override, they will need anywhere between a simple majority to a unanimous vote. Also, if they want to raise your taxes, they would have to ask first by a public referendum.
Calculate you new taxes below:
http://www.sptimes.com/2007/webspecials07/graphics/taxbill-calc/
Tuesday, June 12, 2007
Homeowners, renters, and visitors:
If you will be in Florida at any time between now and November, you need to have a hurricane plan in hand. Sometimes these hurricanes spawn in the Gulf of Mexico and cause widespread cancelleations and traffic jams - what will you do then?
From www.PinellasCounty.org:
Pinellas County’s 2007 Hurricane Guide, Surviving the Storm, Releases Countywide June 12
Pinellas County will release its 2007 hurricane planning guide, Surviving the Storm, June 12 to 14. The headlining message “It’s Everyone’s Responsibility,” stresses citizen preparation for the active season forecasters have predicted. Surviving the Storm, Pinellas County government’s official hurricane guide, includes a unique decision-making flowchart, preparation and safety tips, a special needs page, evacuation maps, shelter lists, pet information, contact numbers and much more.
Neighbors and friends, please plan accordingly...
If you will be in Florida at any time between now and November, you need to have a hurricane plan in hand. Sometimes these hurricanes spawn in the Gulf of Mexico and cause widespread cancelleations and traffic jams - what will you do then?
From www.PinellasCounty.org:
Pinellas County’s 2007 Hurricane Guide, Surviving the Storm, Releases Countywide June 12
Pinellas County will release its 2007 hurricane planning guide, Surviving the Storm, June 12 to 14. The headlining message “It’s Everyone’s Responsibility,” stresses citizen preparation for the active season forecasters have predicted. Surviving the Storm, Pinellas County government’s official hurricane guide, includes a unique decision-making flowchart, preparation and safety tips, a special needs page, evacuation maps, shelter lists, pet information, contact numbers and much more.
Neighbors and friends, please plan accordingly...
Tuesday, June 05, 2007
UPDATE UPDATE
Just released...
Legislative leaders agree to presidential primary tax relief voteTALLAHASSSEE, Fla. (AP) –
June 5, 2007 – Voters would get a chance to approve property tax relief and restructuring proposals during the Jan. 29 presidential primary election, legislative leaders agreed Monday. Rep. Dean Cannon, who chairs a joint select committee on property taxation, announced the agreement during the panel’s last scheduled meeting before a special legislative session set for June 12-22. Cannon, though, said another meeting may be held the day before the special session.
The election date agreement between House Speaker Marco Rubio, R-West Miami, and Senate President Ken Pruitt, R-Port St. Lucie, follows their approval last week of a basic outline for the pending property tax reduction and overhaul.“There is already a statewide election on that date,” Cannon, R-Winter Park, said. “There will be no additional cost to the people of Florida to have the election.”
The Legislature, during its regular session that ended a month ago, passed a new law that moved the primary up from March so that Florida would have more influence on the selection of presidential candidates.Gov. Charlie Crist made a brief appearance before the committee shortly after returning Monday from a trade mission to Israel and Jordan, where he said he ran into a Florida couple who urged him to cut taxes.
Crist greeted the lawmakers with “shalom,” the Hebrew word for hello, and thanked them for their hard work on the tax issue.“It’s complex and it’s difficult. Most importantly, it is very important to the people of our state,” he said.
The committee then heard presentations on some secondary property tax issues but took no action. They included a non-controversial proposal to exempt the first $25,000 of value on equipment and other personal property that taxes businesses.
The panel also discussed options for providing additional tax breaks to affordable housing, low-income senior citizens and working waterfronts such as marinas and commercial and charter fishing docks.Piggybacking a vote on one or more amendments to the Florida Constitution onto the presidential primary also would give local governments plenty of time to comply with the revisions before their next budget year begins Oct. 1, 2008, Cannon said.
If voters reject the proposals – it takes 60 percent approval to amend the constitution – lawmakers also would have time to offer them something else on the November 2008 general ballot, he said.Cannon said putting property taxes on the ballot at the same time that presidential candidates are seeking Florida primary votes also may make them more sensitive to issues important to the Sunshine State.
The long-term constitutional approach to which Rubio and Pruitt have agreed would do away with the existing $25,000 homestead exemption for primary homes and, for most homeowners, the benefits they get from the Save Our Homes Amendment, which limits increases in homestead assessments to 3 percent annually.Instead, primary homeowners would get a tiered, percentage-based super exemption. For example, the first $100,000 of a home’s value might be 70 percent exempt, the next $100,000 would be 50 percent exempt and so on. Homeowners, though, would be able to keep their Save Our Homes benefits if those are better than the super exemption.The percentages will be worked out after other details of the legislation are agreed to, Cannon said.
Pruitt and Rubio also have agreed to short-term property tax relief the Legislature can pass immediately without a constitutional amendment.It would include cuts linked to how much each local government has increased taxes in recent years. Cities and counties that raised taxes the most would have the biggest cuts.Future taxes then would be capped, but local government bodies could exceed the limit either through a vote of something more than a majority or by putting the issue before voters.
Details haven’t yet been worked out.The leaders also have agreed to exempt schools from the tax cuts.
Just released...
Legislative leaders agree to presidential primary tax relief voteTALLAHASSSEE, Fla. (AP) –
June 5, 2007 – Voters would get a chance to approve property tax relief and restructuring proposals during the Jan. 29 presidential primary election, legislative leaders agreed Monday. Rep. Dean Cannon, who chairs a joint select committee on property taxation, announced the agreement during the panel’s last scheduled meeting before a special legislative session set for June 12-22. Cannon, though, said another meeting may be held the day before the special session.
The election date agreement between House Speaker Marco Rubio, R-West Miami, and Senate President Ken Pruitt, R-Port St. Lucie, follows their approval last week of a basic outline for the pending property tax reduction and overhaul.“There is already a statewide election on that date,” Cannon, R-Winter Park, said. “There will be no additional cost to the people of Florida to have the election.”
The Legislature, during its regular session that ended a month ago, passed a new law that moved the primary up from March so that Florida would have more influence on the selection of presidential candidates.Gov. Charlie Crist made a brief appearance before the committee shortly after returning Monday from a trade mission to Israel and Jordan, where he said he ran into a Florida couple who urged him to cut taxes.
Crist greeted the lawmakers with “shalom,” the Hebrew word for hello, and thanked them for their hard work on the tax issue.“It’s complex and it’s difficult. Most importantly, it is very important to the people of our state,” he said.
The committee then heard presentations on some secondary property tax issues but took no action. They included a non-controversial proposal to exempt the first $25,000 of value on equipment and other personal property that taxes businesses.
The panel also discussed options for providing additional tax breaks to affordable housing, low-income senior citizens and working waterfronts such as marinas and commercial and charter fishing docks.Piggybacking a vote on one or more amendments to the Florida Constitution onto the presidential primary also would give local governments plenty of time to comply with the revisions before their next budget year begins Oct. 1, 2008, Cannon said.
If voters reject the proposals – it takes 60 percent approval to amend the constitution – lawmakers also would have time to offer them something else on the November 2008 general ballot, he said.Cannon said putting property taxes on the ballot at the same time that presidential candidates are seeking Florida primary votes also may make them more sensitive to issues important to the Sunshine State.
The long-term constitutional approach to which Rubio and Pruitt have agreed would do away with the existing $25,000 homestead exemption for primary homes and, for most homeowners, the benefits they get from the Save Our Homes Amendment, which limits increases in homestead assessments to 3 percent annually.Instead, primary homeowners would get a tiered, percentage-based super exemption. For example, the first $100,000 of a home’s value might be 70 percent exempt, the next $100,000 would be 50 percent exempt and so on. Homeowners, though, would be able to keep their Save Our Homes benefits if those are better than the super exemption.The percentages will be worked out after other details of the legislation are agreed to, Cannon said.
Pruitt and Rubio also have agreed to short-term property tax relief the Legislature can pass immediately without a constitutional amendment.It would include cuts linked to how much each local government has increased taxes in recent years. Cities and counties that raised taxes the most would have the biggest cuts.Future taxes then would be capped, but local government bodies could exceed the limit either through a vote of something more than a majority or by putting the issue before voters.
Details haven’t yet been worked out.The leaders also have agreed to exempt schools from the tax cuts.
Monday, June 04, 2007
So just what is going on in the housing market?!? Here's a brief summation of what we are looking at IN THE SHORT-TERM:
- Slightly decreasing Inventory with little absorption
- Selling prices have dipped 20% - 35% in some cases, which is a return to 2003-2004 pricing levels.
- Interest rates have slowly increased to an 8-month high (6.37% avg on a 30 FRM in the Southeast sector - www.freddiemac.com)
- Little movement expected for interest rates in the future (relatively stable indicators)
- Insurance rates appear to be a fact of life now, as much as $3+ gas
- Tax relief is on the way (hopefully)
June will be a telltale month for Florida's housing market - I expect a stabilization in the marketplace SHOULD the correct tax relief legislation be passed and voted in soon thereafter.
Sunday, May 27, 2007
I had a client approach me about making an offer on a Beach condo the other day. Problem is, the owners had recently bought it and paid just about what the market is bearing today. So how do I "sweeten" the offer for the seller and still get it at the price my buyer believes it is worth?!?
Hmmm...I sat down to think about it - what would I want to see if I were selling my property and an offer came in for LESS than list price? Here are some ideas to consider:
Happy Hunting!
Rich
Hmmm...I sat down to think about it - what would I want to see if I were selling my property and an offer came in for LESS than list price? Here are some ideas to consider:
1) Write up an offer in an amount using non-rounded numbers, i.e. $237,251. During the days of multiple offers, it would leave an impression upon the seller, thereby increasing your chances of winning the bidding war. Nowadays, it will intrigue them because they aren’t round numbers and the sellers will wonder "Why" and how you arrived at the number you have offered them.
2) Offer to pay a certain amount, say up to $5000, of the Seller’s closing costs. This tactic is mainly used by buyers to get additional funds at closing. In this instance, it shows generosity and will be viewed as additional money the sellers will "receive"
3) Buyers making a substantial lower-than-list-price offer need to make that offer as clean and hassle-free for the seller as possible. Therefore, if you are pretty sure there are no major issues with the property (easy for newer condos and TH's), then make the offer “As-Is with Right to Inspect and Right to cancel based on inspection results”. Even if something does turn up, you can walk away. Not obligating a Seller to spend $10,000 on a new roof is incentive!
4) Make the closing date as soon as feasible so it is tempting for them. Nothing tantalizes the senses like a quick close. Very similar to dangling a carrot in front of them.
5) ALWAYS include your Mortgage Pre-Approval letter to make the offer genuine. A knowledgeable listing agent will contact the lender to make inquiries.
6) Here’s where you can win them over….offer a SIZEABLE Escrow deposit to show you are a serious, bonified buyer. Nothng beats a sure thing, and putting up a sizable amount of escrow shows willingness to consumate the transaction.
7) Tighten up some of the deadlines, i.e. Home inspection period, mortgage commitment period, Condo Association application period, etc. Make sure your agent (representing the Buyer's interest) can follow through and meet the deadlines. Your agent should have a good relationship with reputable home inspectors (I employ Diamond Building Inspections), appraisers (Marvin Dever), and Pest control companies. They will make or break your sale!
8) Here’s an outside-the-box idea that will be of good use to a Beach/Vacation property buyer who doesn't intend to occupy full-time…since it’ll be a rental anyway, offer them 2 - 4 weeks of rent-free occupancy to be used by them or whomever they designate for a certain number of years, say 3 years. The cost is very minimal to you, as there is a chance they may not use all 4 weeks, and they will see extra value in being able to revisit their former home. Just an idea.
9) Offer to pay the Seller's moving costs. Not only is moving costly in both time and money, but it disrupts life entirely. Maybe the seller was planning to move themselves to save money - imagine if your offer included $2000 to pay for movers. Or just offer a limited amount of money to assist them with renting a moving truck, paying for gas, etc.. A little unconventional, but it will have value for owners. NOTE: Do not make the deal with the movers on the Seller's behalf. Have the seller do it and compensate them at closing - it limits your liability and chance of losing the money should the property not close.
10) CASH IS KING! If you have the cash on hand, use it to purchase the property and then re-fi a couple of months after the closing. If you lack the necessary funds but have a family member who can help, have them draft a promissory note for you to sign in exchange for the cash. Sellers will accept much lower prices when the offer is all cash.
11) There is one more thing you could do. I have seen buyer clients write a short letter to the sellers detailing who they are (the buyers) and why they fell in love with the property, etc. Seller's want to know they aren't selling their most-prized possession to someone who doesn't value it like they do or will not care for it like they did. A bit cheesy, but it only needs to be a part of a larger offer to work.
Happy Hunting!
Rich
Monday, May 21, 2007
Ok, this is not your annual "Run for cover - here come the Hurricanes!" terror-filled post. Instead, I urge you to take the following steps to make YOUR 2007 hurricane season less stressful.
As a 26 year resident of Pinellas County, I can honestly say that I can remember only 2 storms of notable strength which directly impacted our County, one of which wasn't even a Hurricane - Hurricane Elena (en.wikipedia.org/wiki/Hurricane_Elena) and the No-Name Storm of '02/'03. Neither of them were particularly as damaging as Recent storms such as Charley, Katrina, or even Andrew. They were a mostly headache for area residents.
Here are a few things you can do as a homeowner to prepare for the 2007 hurricane season:
As a 26 year resident of Pinellas County, I can honestly say that I can remember only 2 storms of notable strength which directly impacted our County, one of which wasn't even a Hurricane - Hurricane Elena (en.wikipedia.org/wiki/Hurricane_Elena) and the No-Name Storm of '02/'03. Neither of them were particularly as damaging as Recent storms such as Charley, Katrina, or even Andrew. They were a mostly headache for area residents.
Here are a few things you can do as a homeowner to prepare for the 2007 hurricane season:
- CLEAN YOUR GUTTERS! A free-flowing gutter system will ensure the enormous amounts of rain are conveyed off the structure in a rapid, expedient manner.
- TRIM THE TREES! Ever seen the palm trees with only 2-4 fronds sticking out of the top? That's called a "Hurricane Cut" and actually allows the Palm tree to offer less wind resistance, thus increasing it's chance of weathering the storm.
- CLEAR YARD DEBRIS! Make sure you have a spot in the house or garage for items such as lawn furniture, grills, tools, and even potted plants. They can become deadly missiles during a rough storm and may even impact your neighbors home.
- REINFORCE YOUR GARAGE DOOR! Studies have shown that Garage Doors are the the weakest structural areas of any home and are also the entry point for the destructive winds that destroy homes. Consider reinforcing your garage door or simply replacing it.
- FOOD AND WATER! When you are doing your weekly Grocery shopping, pick up a few extra gallons of water each trip and after a month or 2 you should have at least enough water to last you for a week. Consider having at least 2 gallons per day per person.
- PAPERWORK! Take this time to make copies of valuable paperwork such as your homeowners policy, paperwork from your home's purchase, SS cards, and any valuable assets such as bank statements, securities, and credit card info. Having this info on hand in a safe place will make weathering any storm easier.
- HAVE A PLAN! What would you do if a Category 3 storm were on a collision-course with Pinellas County? My wife and I have decided to ride out any storm that is a weak category 3 or less. Anything stronger and we will drive to her families house in SC. What would you do???
As the hurricane season approaches, a little forethought can save you time and money!
Subscribe to:
Posts (Atom)


